LOAN PROCESS · GTG FINANCIALOctober 2026 · Santa Rosa, CA WATCH THE 62-SECOND VERSIONWatch on…
Waiting for Rates to Drop Could Cost You the House
| BUYER PLAYBOOK · GTG FINANCIALOctober 2026 · Santa Rosa, CA |
WATCH THE 90-SECOND VERSION
TL;DR: WHAT’S IN THIS POST
- Why the “rates are down” headline usually arrives after the best window has already opened
- What happens to prices, showings, and seller concessions when sidelined buyers all come back at once
- Why the move is to buy the asset when you can, then restructure the debt later with a refinance if the numbers work
- The one thing that decides whether you get that window: being fully pre-approved and actively looking before it opens
The Headline Is the Lagging Indicator
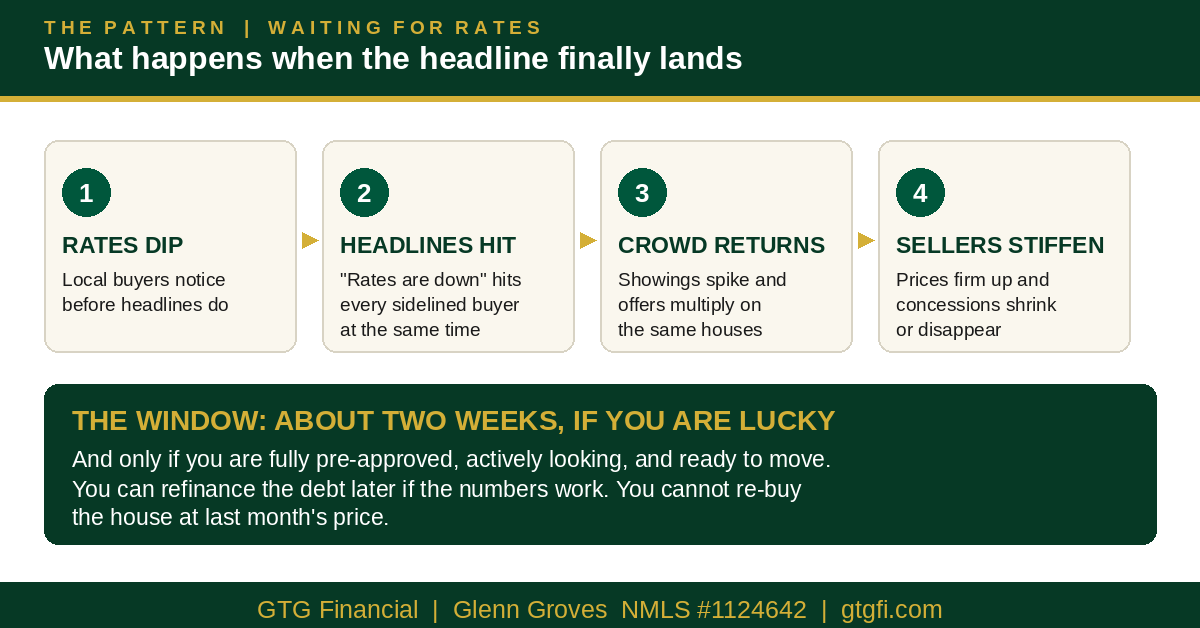
Here is the part most buyers get backwards. As soon as mainstream media comes out with “rates are down,” it is usually too late to be first.
I see it in real time. Before rates moved recently, I was out looking with five or six different groups of buyers. Then the headlines hit, and it thinned out fast, because a lot of buyers decided to wait for one more drop. They are chomping at the bit, just like everyone else, all waiting for the same signal.
The problem is that signal is public. When it fires, it fires for everybody at the same time.
What Happens When Everyone Un-Waits at Once
Rates drop, and three things tend to happen in a hurry:
- House prices firm up or go up. More buyers chasing the same houses means sellers do not have to be flexible.
- Listing agents stiffen up. They see the showing traffic and the calls coming in. They know rates just dropped half a percent. Concessions get harder to get, not easier.
- Your negotiating window shrinks to days, not months. In the video I called it maybe a two week window, if you are lucky. That is not a shopping season. That is a sprint.
None of that is guaranteed in any single week, and rates do not move in a straight line. But the pattern is consistent: demand reacts faster than most buyers do.
Buy the Asset, Restructure the Debt
The line from the video is the whole strategy: get the asset while you can, so you can restructure the debt while you own it, instead of restructuring the debt by adding more of it later at a higher price.
In plain English, that second part is a refinance. If you buy the right house at a workable payment today, and rates improve later, you can look at refinancing into the better rate while you already own the home.
Two honest caveats:
- A refinance is never guaranteed. It depends on rates at that time, your credit, your income, and the value of the home, and it has to pass underwriting then.
- Do not buy a house you cannot afford today counting on a refinance to save it. The payment has to work now. The refinance is upside, not the plan.
“
Get the asset while you can, so you can restructure the debt while you own it, instead of restructuring the debt by adding more of it later at a higher price.
GLENN GROVES, GTG FINANCIAL
Be the Tip of the Spear
You cannot wait your way into that window. You have to be ready before it opens:
- Fully pre-approved, not just pre-qualified. Documents in, income and assets verified, file actually reviewed.
- Actively looking, with your agent, in the price range you are approved for.
- Clear on your walk-away numbers ahead of time, so you are deciding, not scrambling, when a house fits.
If you are wondering whether waiting makes sense for your specific numbers, let us run them both ways: buy now at today’s price and payment, versus the same house after a rate drop moves the price and kills the concessions. That math is a lot clearer than a headline.
Start a pre-approval here: 1595076.my1003app.com/1124642/register
Want your buy-now versus wait math run on real numbers?
Send me the price range and the payment you are comfortable with. I will run both paths, today’s price and payment, and the same house after a rate drop moves the market.
Start Hereor call (707) 546-0440
Glenn Groves
Mortgage Broker | GTG Financial | Santa Rosa, CA
NMLS #1124642 | gtgfi.com
GTG Financial, Inc. NMLS #1595076 | CA DRE #02029711. Equal Housing Opportunity. For educational purposes only. Not a commitment to lend. Subject to credit approval and underwriting. Rates and terms subject to change without notice. Individual rates vary based on credit profile, property type, occupancy, loan amount, and other factors. nmlsconsumeraccess.org

Related Posts