LOAN PROCESS · GTG FINANCIALOctober 2026 · Santa Rosa, CA WATCH THE 62-SECOND VERSIONWatch on…
Buying in Sonoma County? Two Things I Check Before You Make an Offer
| BUYER PLAYBOOK · GTG FINANCIALOctober 2026 · Santa Rosa, CA |
WATCH THE 60-SECOND VERSION
TL;DR: WHAT’S IN THIS POST
- Check one: the fire map, and a real insurance quote, before you fall for the house
- Check two: the actual tax bill, which is public record, instead of a rule-of-thumb tax estimate
- Why a special assessment, like a watershed bond out at the Russian River, can push the real tax cost well past the estimate
- The simple split we use: you get insurance quotes, I pull the taxes, then we decide together if it still works
The Payment You Quote Is Not the Payment You Get
Every buyer runs the same first math: price, down payment, rate, payment. In Sonoma County, two line items sit underneath that math and can blow it up after you are already emotionally in: homeowners insurance, and property taxes.
Neither one is a surprise if you check them early. Both are checkable before you write an offer. Here is how I do it.
Check One: The Fire Map, Then a Real Insurance Quote
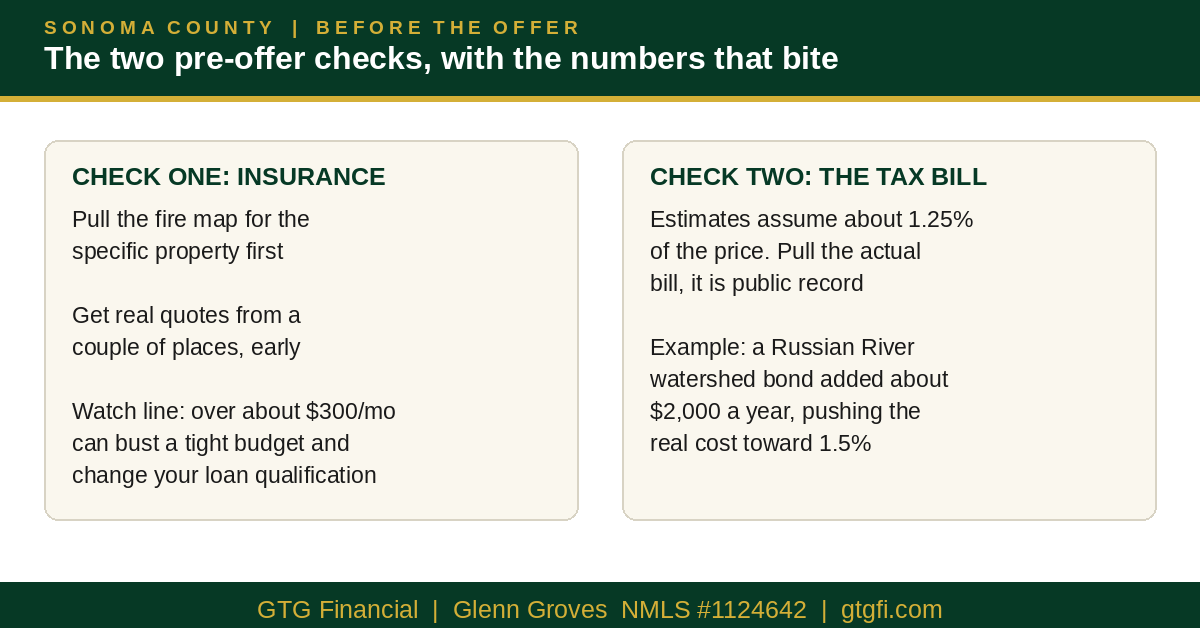
Start with the fire map for the specific property. A lot of Sonoma County, out at the river, in the hills, in the wildland edge of our towns, sits in or near high fire severity zones, and insurers price that, or decline it.
Then get an actual quote. Not a guess, not last year’s number from the seller, a quote, from a couple of different places.
Here is the conversation I have in the video: if we are real tight on a property, and insurance comes back over, say, $300 a month, it can bust the budget. I am not comfortable, and you should not be either. If the quotes are outlandish, that is information. It may mean this is not the right property, and it is far better to learn that before your deposit and contingencies are in play than after.
Your insurance cost also feeds your loan qualification, because it is part of your monthly housing expense. An extra $300 a month is not just annoying. It changes the debt-to-income math.
“
You go get insurance quotes. I pull the taxes. Then we meet back and answer one question honestly: does this still look good?
GLENN GROVES, GTG FINANCIAL
Check Two: Pull the Actual Tax Bill
Property taxes are public record. I pull the tax bill on the property and make sure we are in the zone of what we were estimating.
The usual estimating shortcut is around 1.25% of the price. Sometimes the real bill says otherwise. Out at the river, for example, I have pulled bills where a Russian River watershed bond added about $2,000 a year to everybody’s tax bill on top of the base. Run that out and the effective cost is closer to 1.5%, not one and a quarter. You look at that and go, whoa, that is more.
That gap matters twice. It raises your monthly escrow payment, and it can show up as a shortage later if the loan was set up on the low estimate.
Important detail: a tax bill on the current owner’s property reflects the current assessed value and the assessments on that parcel today. After you buy, the county reassesses to your purchase price, so use the bill to find the extra assessments and the rate structure, then apply them to your price. That is exactly the exercise we do together.
How We Run It
It is a simple split, and it is the close of the video:
- You: go get insurance quotes on the specific house.
- Me: I pull the tax bill and rebuild the tax estimate off the real parcel.
- Together: we meet back and answer one question honestly. Does this still look good?
If it does, you write the offer knowing your real payment. If it does not, you found out for the cost of a phone call and a public record, instead of mid-escrow.
Buying in Sonoma County and want both checks run on a house you are serious about? Send me the address. That is a pre-offer conversation, not a sales pitch.
Start a pre-approval here: 1595076.my1003app.com/1124642/register
Serious about a Sonoma County house?
Send me the address before you write the offer. I will pull the tax bill and we will get real insurance quotes, so the payment you fall for is the payment you get.
Start Hereor call (707) 546-0440
Glenn Groves
Mortgage Broker | GTG Financial | Santa Rosa, CA
NMLS #1124642 | gtgfi.com
GTG Financial, Inc. NMLS #1595076 | CA DRE #02029711. Equal Housing Opportunity. For educational purposes only. Not a commitment to lend. Subject to credit approval and underwriting. Rates and terms subject to change without notice. Individual rates vary based on credit profile, property type, occupancy, loan amount, and other factors. nmlsconsumeraccess.org

Related Posts