LOAN PROCESS · GTG FINANCIALOctober 2026 · Santa Rosa, CA WATCH THE 62-SECOND VERSIONWatch on…
VA Funding Fee: It May Be Waived for You
| VA LOANS · GTG FINANCIALOctober 2026 · Santa Rosa, CA |
WATCH THE 40-SECOND VERSION
TL;DR: WHAT’S IN THIS POST
- What the VA funding fee is, and why VA loans have it instead of monthly mortgage insurance
- How much it is on a purchase loan today
- Who is exempt, in the VA’s own terms
- Where the answer shows up: your Certificate of Eligibility, which I can pull in about 30 seconds
The Biggest Cost Most VA Buyers Do Not Have to Pay
The biggest hook with a VA loan is what is called the funding fee. It is what the VA charges to guarantee the loan, and it is a big part of why the program can offer 0% down, no monthly mortgage insurance, and rates that are often lower than conventional.
It is a one-time fee, and most buyers finance it into the loan instead of paying it in cash at closing. That makes it easy to miss. It is in there, quietly making the loan balance bigger, unless you are exempt.
How Much Is It?
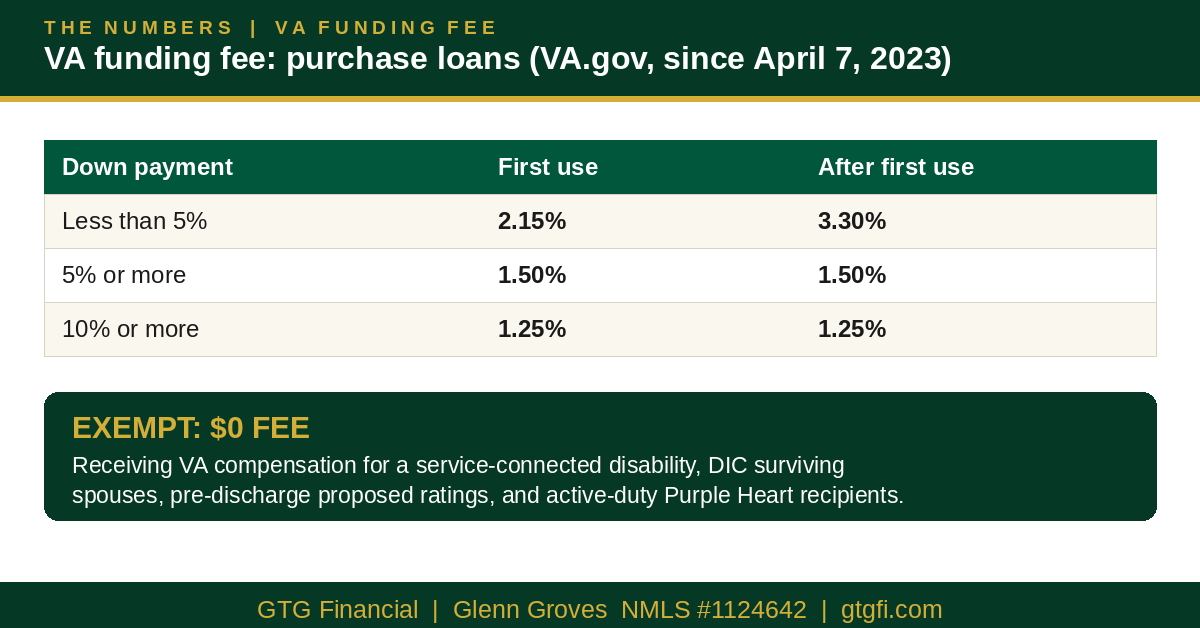
For purchase and construction loans, at the rates VA has had in effect since April 7, 2023:
| Down payment | First use | After first use |
|---|---|---|
| Less than 5% | 2.15% | 3.30% |
| 5% or more | 1.50% | 1.50% |
| 10% or more | 1.25% | 1.25% |
On a $500,000 loan with nothing down, first use, that is $10,750 financed into the loan. Real money, and worth checking before you assume you owe it.
Source: VA, “VA funding fee and loan closing costs,” va.gov.
Who Gets It Waived
In the video I said it the short way: unless you are a veteran rated 10% or more disabled, and here is the precise version, because the VA’s wording is what controls.
You do not have to pay the funding fee if any of these apply to you:
- You are receiving VA compensation for a service-connected disability
- You are eligible to receive that compensation, but you are receiving retirement or active-duty pay instead
- You are receiving Dependency and Indemnity Compensation (DIC) as the surviving spouse of a veteran
- You are a service member with a proposed or memorandum rating before closing, from a pre-discharge claim
- You are an active-duty service member who provides evidence, on or before closing, of receiving a Purple Heart
Why the video says “10% or more”: VA disability compensation payments start at a 10% rating. A 0% rating means the VA recognizes the condition as service-connected, but it does not pay monthly compensation for it, so a 0% rating on its own does not trigger the waiver. If you are getting compensated, you are exempt.
“
It is in there, quietly making the loan balance bigger, unless you are exempt.
GLENN GROVES, GTG FINANCIAL
It Is Printed on Your COE
This is not a judgment call at the closing table. Your exemption status shows up on your Certificate of Eligibility (COE), which will say Exempt or Non Exempt for the funding fee.
I can pull your COE for you. I have access to the VA system, and it takes about 30 seconds. That is worth doing at the very start, for two reasons:
- If you are exempt, your Loan Estimate should not carry a funding fee at all, and we want that right from the first disclosure, not fixed at the end.
- If your rating is granted later with an effective date before your loan closed, you may be due a refund of a fee you already paid. That is a VA process, and it starts with knowing your status.
If you are a veteran thinking about buying, let us pull the COE first and build the numbers around what you actually owe, not the default.
Start here: 1595076.my1003app.com/1124642/register
Find out if your funding fee is $0
I can pull your Certificate of Eligibility in about 30 seconds and tell you whether it says Exempt before we build any numbers.
Start Hereor call (707) 546-0440
Glenn Groves
Mortgage Broker | GTG Financial | Santa Rosa, CA
NMLS #1124642 | gtgfi.com
GTG Financial, Inc. NMLS #1595076 | CA DRE #02029711. Equal Housing Opportunity. For educational purposes only. Not a commitment to lend. Subject to credit approval and underwriting. Rates and terms subject to change without notice. Individual rates vary based on credit profile, property type, occupancy, loan amount, and other factors. nmlsconsumeraccess.org

Related Posts